D.R. Horton in Temple & Belton: The Straight Review
Does D.R. Horton give you enough home for the money? Taylor’s take on the homes he saw was basic finishes, good product for the price. Explore the local communities, see what comes with the home and understand the financing offer. If a home catches your eye, Taylor can help you compare it with the alternatives.
Four community examples
Observed
- Pepper Creek Crossing
- Advertised from$212,735
- Pecan Creek
- Advertised from$218,990
- Mesa Ridge
- Advertised from$332,990
- Homestead
- Advertised from$376,035
Four community examples. Advertised starting prices observed September 23, 2026; not current inventory or a complete Temple–Belton list.
Is D.R. Horton a good choice in Temple or Belton?
D.R. Horton may be worth a closer look if you are comfortable with a simpler finish package and the home compares well with your other options. The useful tradeoff is what you get for the money: included features you would keep, changes you would pay for and the complete purchase and financing costs. Taylor can help put those differences side by side.
The offer checked October 18: DHI Mortgage advertised 5.50% fixed FHA and VA financing on the Pecan Creek, Pepper Creek Crossing and Mesa Ridge pages, with FHA APR 6.212% and VA APR 5.657%. Eligible principal-residence homes must be under contract on or after October 1, 2026 and close by January 29, 2027. Approval, available funds, points and closing costs matter; see the terms, then compare two rates.
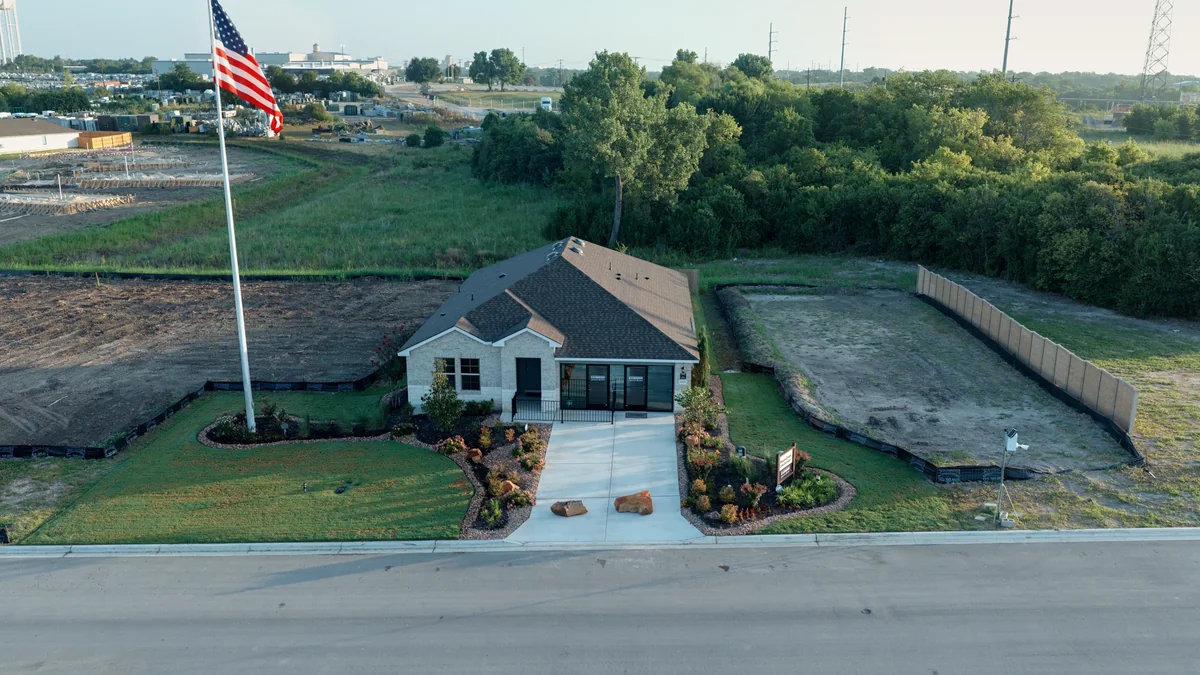
- Find your starting point: explore the communities and Taylor’s local photos below.
- Understand the offer: see the dated terms and compare two rates using your own figures.
- Look beyond the model: use the included-features, inspection and ownership-cost sections to spot the important questions.
- Get help with the comparison: bring a home you like, or start with your budget and moving plans.
What financing offer is advertised now?
Official offer checked October 18, 2026: D.R. Horton’s Pecan Creek, Pepper Creek Crossing and Mesa Ridge pages carried a DHI Mortgage promotion for certain homes, with the following advertised 30-year fixed-rate examples:
| Loan program | Interest rate | APR | Advertised down payment |
|---|---|---|---|
| FHA, 30-year fixed | 5.50% | 6.212% | 3.5% |
| VA, 30-year fixed | 5.50% | 5.657% | 0% |
The published window is a contract dated October 1, 2026 or later, with closing by January 29, 2027. The advertised rate requires DHI Mortgage and an eligible home purchased as a primary residence. Approval, available rate funds and property restrictions still apply; points may be required and additional closing costs apply, and the offer may not combine with other incentives. These are advertised examples, not a quote for your home or loan.
Compare the whole offer. A lower rate is useful only in the context of the home’s price, cash needed to close and monthly ownership costs. Taylor can help you compare the builder’s written offer with the alternatives you are considering. Your lender supplies the loan terms and confirms whether you and the home qualify.
Official sources checked October 18, 2026: Pecan Creek offer, Pepper Creek Crossing offer and Mesa Ridge offer. APR means annual percentage rate. The source disclosure is marked revised October 6, 2026.
Earlier advertisement recorded September 23, 2026
Historical comparison only. This is the earlier advertised offer, not a current quote. The new advertisement does not establish whether a previously approved or locked loan changed.
The official Pecan Creek and Pepper Creek Crossing pages displayed the following DHI Mortgage advertisement on September 23, 2026. This records an advertised offer; it does not confirm remaining rate-pool funds, approval or eligibility for a particular address.
| Advertised loan | Interest rate | APR | Example scope |
|---|---|---|---|
| FHA fixed, 30 years | 4.99% | 5.697% | Source example: $309,284 loan, 3.5% down and financed 1.75% upfront mortgage insurance. |
| VA fixed, 30 years | 4.99% | 5.142% | Source example: $321,762 loan, 0% down and a financed first-use funding fee of up to 2.15%; eligibility and fee treatment vary. |
Both published APR examples use a $314,990 sales price and the stated program assumptions. They are not universal borrower quotes; your APR, eligibility, fees and payment may differ.
Dates and qualification
The advertisement says contract on or after July 30, 2026 and close by October 30, 2026. It applies to certain homes in select Texas communities, purchased as a principal residence. Credit approval, market conditions, available funds and property restrictions apply. The displayed notice is marked revised July 31, 2026.
Costs and conditions
DHI Mortgage is required for the advertised rate, but the notice says buyers are not required to use DHI to buy a home. Borrower-paid points may be required; additional closing costs apply. The offer may not combine with other incentives. Ask the lender to identify every point, fee and credit in your own Loan Estimate.
The source also mentions USDA availability, but does not provide a separate USDA APR example here. No street-by-street eligible-home list or individual approval is established by this page. Ask the sales representative and loan officer to confirm the address, program, lock expiration and written terms before relying on the advertisement.
An advertised rate is not the whole package
Keep the home price and lender proposal together. Ask for a written comparison of the price, credits and closing costs with each lender. A smaller P&I payment can coexist with higher upfront costs or a different financed balance. Compare actual offers rather than a builder rate against a national average.
Compare two rates (principal and interest)
How much does the rate change principal and interest?
Use the same loan balance and term to isolate the rate difference between two fixed-rate scenarios. Enter the amount actually being financed, including any financed fees. These inputs start blank; they are not a DHI quote, an approval or an estimate of your total housing payment.
Same-loan P&I illustration
Uses 12 monthly payments per year and full amortization over the entered term. The difference is calculated before rounding, so subtracting the displayed payments may differ by one cent. If actual balances, terms or payment structures differ, compare the full Loan Estimates separately.
Enter all four values to compare monthly principal and interest.
Incomplete housing cost: excludes property taxes, homeowners insurance, mortgage insurance, HOA charges, maintenance and separate assessments. Unfinanced fees, down payment and other cash-to-close costs are also outside this calculation. It does not predict escrow changes or the financial result of selling or refinancing.
For the broader decision, use the rent-versus-buy cash-flow guide and the CFPB’s loan-offer comparison steps.
Watch Taylor’s D.R. Horton review
The August 2026 video includes Taylor’s field opinion and the questions he considered before a purchase. Published August 25, 2026, local time.
Filmed in August 2026. The video's 4.50% offer and September 30 deadline are historical claims whose availability has not been re-confirmed for this guide. The 4.99% advertisement recorded September 23 in the earlier-offer note above is a separate observed offer; this guide does not establish that it replaced the video's offer.
Which local communities should you compare first?
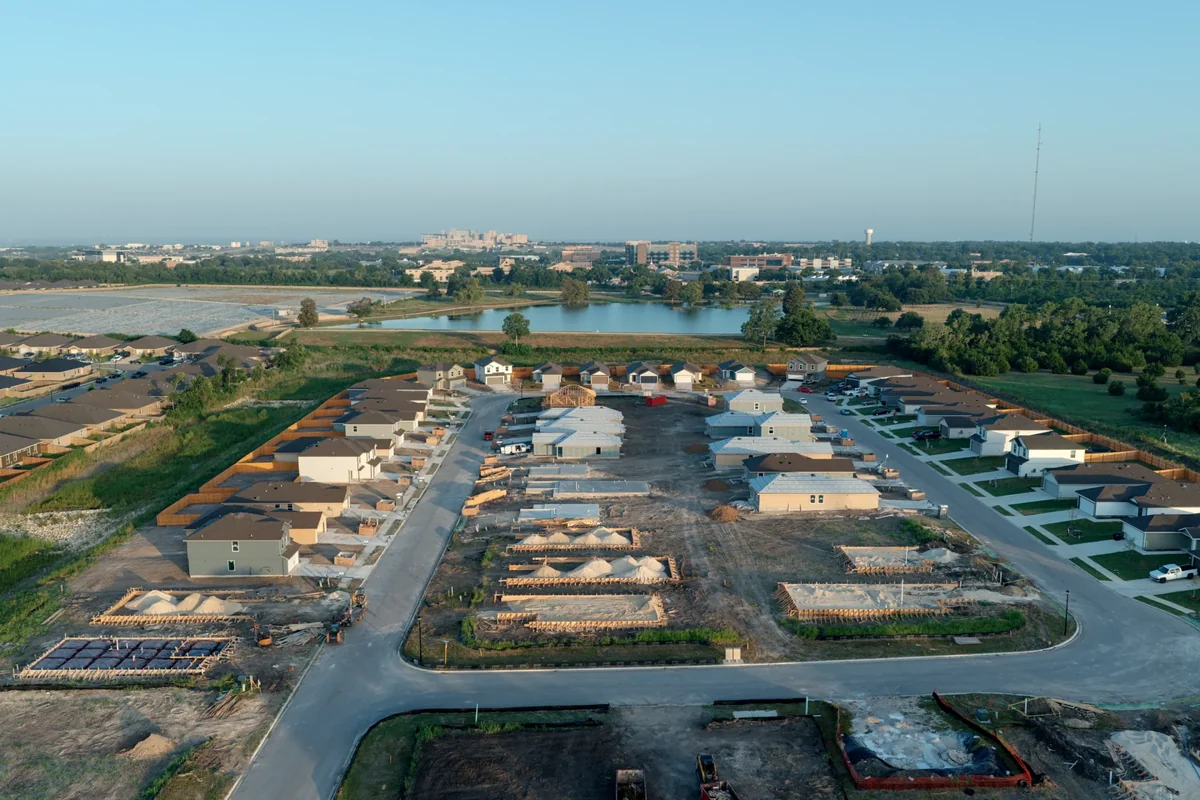
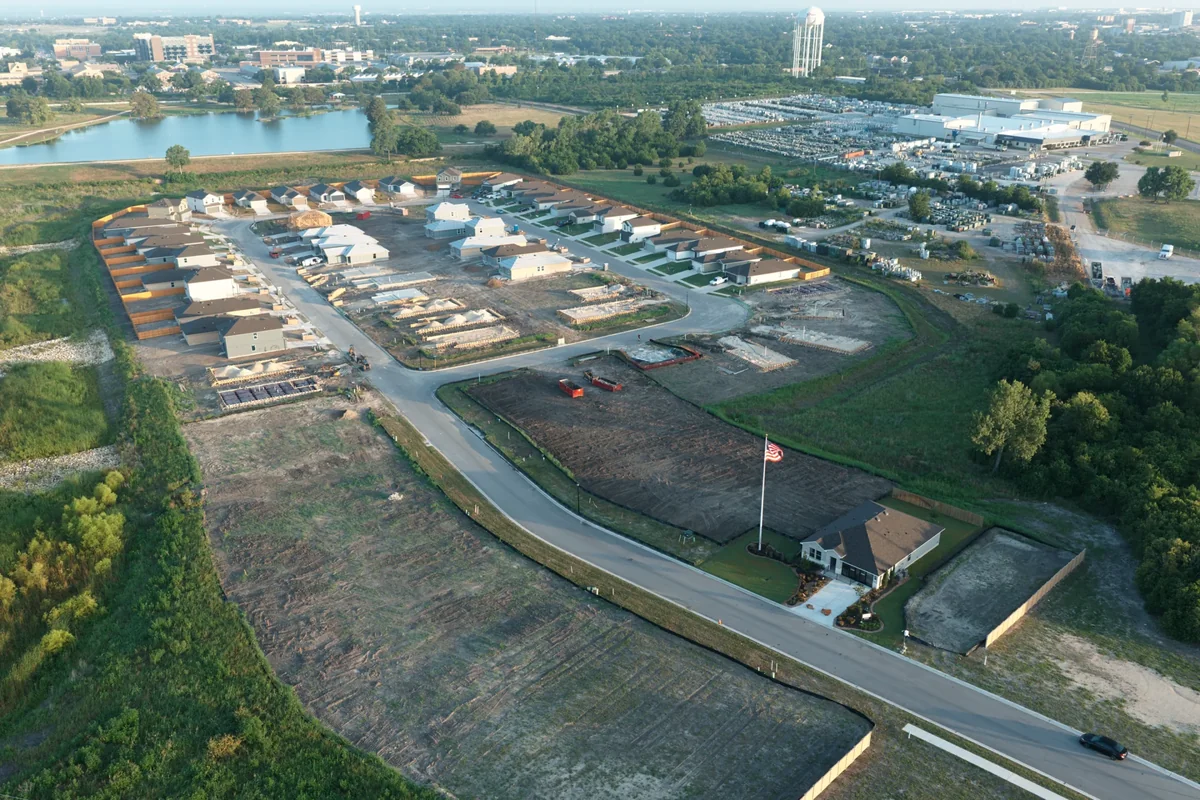
These four Temple-addressed examples were checked on official community pages September 23, 2026. They are a starting shortlist, not a complete Temple–Belton inventory. “From” means the builder’s advertised starting price, not an all-in quote or proof that a particular home is available.
| Community | Mailing location | Advertised from | Source-described product | Starting point for a visit |
|---|---|---|---|---|
| Pepper Creek Crossing Ask Taylor about this community | Temple 76502 | $212,735 | Express · 3–5 bedrooms | 7208 Brookside Blvd · compare the exact plan and location with Pecan Creek. |
| Pecan Creek neighborhood guide | Temple 76504 | $218,990 | Express · 3–5 bedrooms | 1428 Newey Circle · ask which home and included features support your quoted price. |
| Mesa Ridge neighborhood guide | Temple 76502 | $332,990 | Express · community description lists 3–4-bedroom plans | 8736 Yellowcress Drive · current page heading lists 4 bedrooms and “Final Opportunities”; confirm the specific remaining home and plan. |
| Homestead Ask Taylor about this community | Temple 76502 | $376,035 | Tradition · 3–5 bedrooms | 9612 Jett Drive · source advertises three-car garages; compare the actual layout and total price. |
Addresses above identify the builder’s community contact/model location, not an eligible-home list. Floor plans, prices, availability and included items can change. Ask for an address-specific quote with lot charges, options, completion stage and incentives itemized.
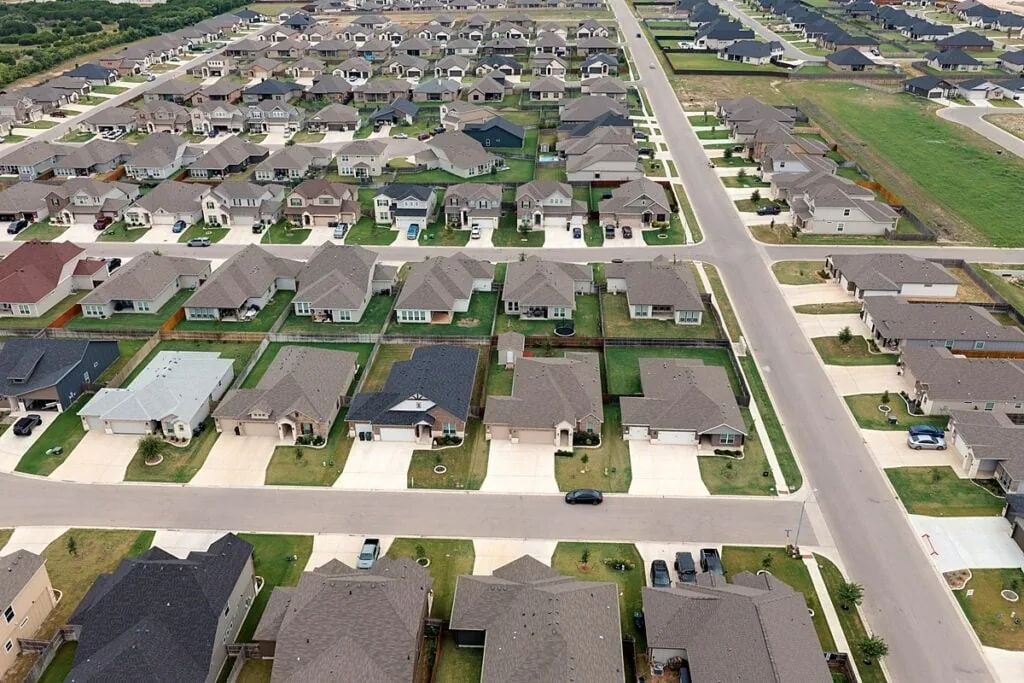
Choose the location before optimizing the loan
Test the actual trip to work at the time you would travel. Confirm school assignment with the district for the home’s address; a Temple mailing address does not settle that question. For a Belton-area comparison, the Three Creeks guide explains its location and property-tax considerations. Confirm whether a D.R. Horton home there is currently available rather than relying on an older “final opportunities” label.
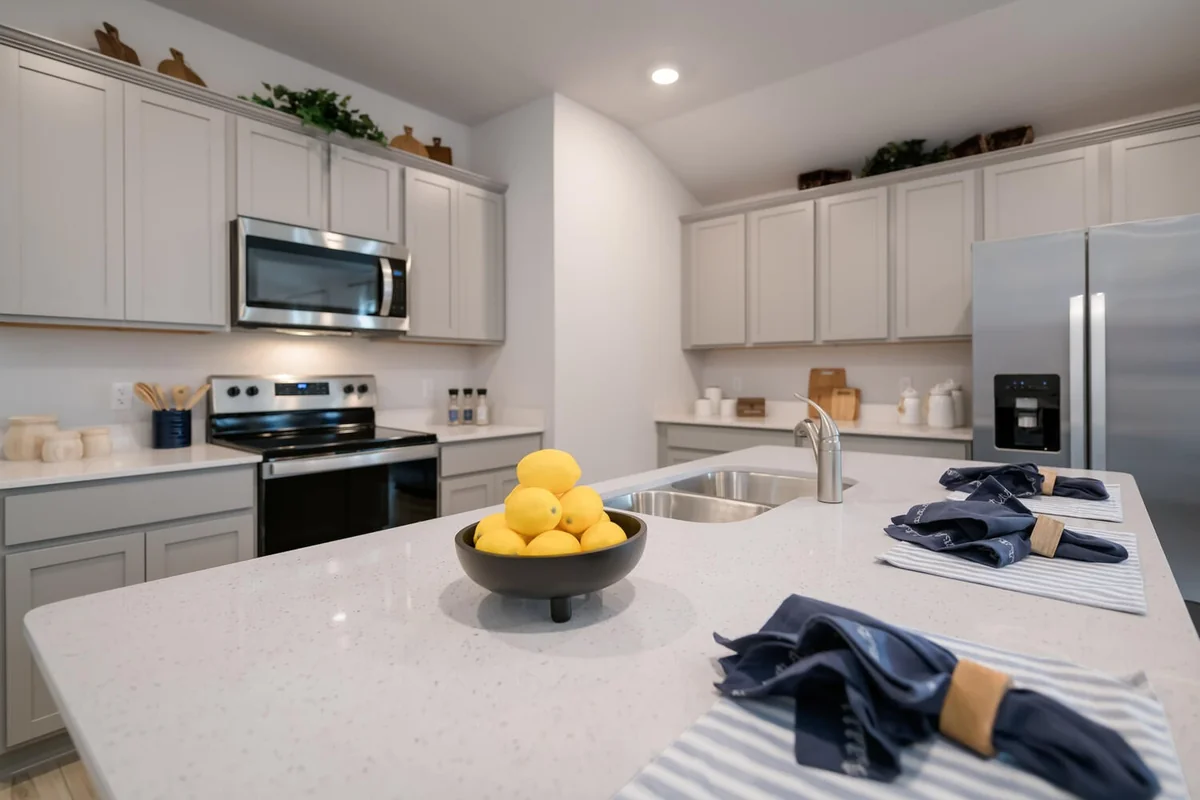
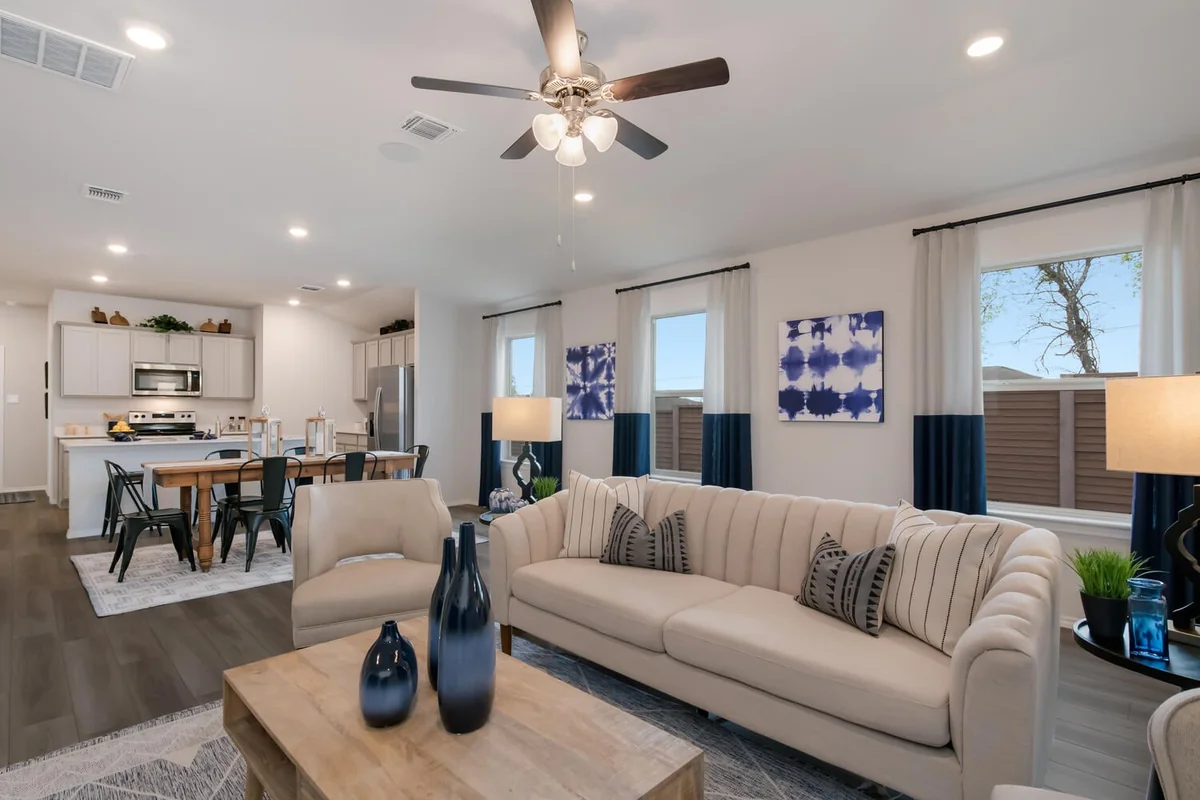
What should you inspect beyond the model-home finishes?
Taylor’s August field take was that the finishes were basic but the price could make sense. Use that as a prompt to compare the exact product. A brand name, series label or staged model does not establish every home’s framing, insulation, HVAC, included appliances or workmanship.
Included specifications
Request the included-features sheet and option list for the address. Identify flooring, counters, appliances, insulation, HVAC, drainage and landscaping. Mark anything shown in a model that is not included.
Changes and timing
Ask which choices are still available at that home’s construction stage, what each costs and what requires written approval. Do not assume a customization request is allowed or prohibited based on another community.
Independent inspection
Get inspection access, permission, notice requirements and deadlines in writing. Ask an independent inspector what can still be inspected at the current stage and how unresolved findings should be documented before closing.
What online complaints can and cannot tell you
A detailed complaint can suggest a question to ask about repairs or response procedures. A national review sample is not a measured defect rate for a Temple community, and a sales-office rating does not establish future warranty service. Compare the specific reported issue with the inspection, contract and warranty for your home.
What costs sit outside the advertised price and P&I?
| Cost | What to obtain | Question before signing |
|---|---|---|
| Property taxes | Actual parcel’s taxing entities, values and applicable exemptions | Is this a land-only record or a completed-home estimate? Which tax year and entities are included? |
| Insurance | Address-specific quote with deductibles and coverage | What premium and deductible can you carry, and what coverage is excluded? |
| HOA and assessments | Current resale/disclosure documents, dues and fees | Are transfer, capital, special or separate district charges included in the budget? |
| Loan and closing | Loan Estimate, written incentives and later Closing Disclosure | Which costs are financed, paid in cash or offset by a credit? |
| Move-in and upkeep | Included-features list and your own spending plan | Which appliances, window coverings, moving costs and repair reserves remain? |
A new build’s land-only tax history may not describe the completed property. Ask the lender how taxes and insurance were estimated and how escrow adjustments could affect the payment; do not assume a fixed Year-2 increase. Use the property-tax guide and entity-level worksheet for the parcel method.
At Three Creeks, the local guide documents a MUD as one part of the tax structure. A MUD line alone does not prove that home’s complete bill is higher than another community’s. Compare all entities and each property’s taxable values, exemptions and other assessments for the same year.
What should the warranty and inspection plan say?
Obtain the warranty booklet that will apply to your home, plus the builder’s written service and emergency-contact procedures. D.R. Horton’s official documents and guides provide a starting route; a sample booklet is not proof of the coverage in your contract.
- Coverage: what is covered, excluded or treated as homeowner maintenance?
- Dates: when does each coverage period start and end?
- Process: who receives notice, how must it be submitted, and what evidence is required?
- Responsibility: which issues go to the builder, an appliance manufacturer or another warranty provider?
- Follow-up: keep inspection reports, photographs, requests and written responses. Consider a further inspection before applicable coverage expires.
An inspection identifies conditions; it does not expand warranty coverage or force a builder to pause construction. Resolve access and notice timing before booking, and use the actual contract and booklet to plan deadlines.
When should you compare another builder or a resale home?
Use the same budget and needs for each home, including the Centex homes you consider: usable layout, lot, location, condition, included items, completion date and complete financing package. A lower rate on one home does not establish better value than a different home with a lower price or different costs.
| Your priority | Useful comparison |
|---|---|
| A lower entry price | Compare a written Pecan Creek or Pepper Creek quote with another available home at the same budget. Include resale options. |
| More space, garage or finish choices | Compare the specific Mesa Ridge or Homestead plan with alternatives that satisfy the same requirements; a higher price or series name is not a quality test. |
| A fixed move date | Ask for written completion and closing expectations, the conditions that can change them, and the cost of temporary housing if needed. |
| A preferred location or school assignment | Check the actual address, route and district assignment before comparing financing. |
You can compare Temple home builders for questions to ask across builders, the new-construction guide for local options, and new construction versus resale for the broader choice.
What does “good product for the price” mean for your search?
Taylor Dasch · EG Realty · August 15, 2026 field opinion
Taylor described the finishes as basic and the homes he saw as a “good product for the price.” That is his assessment of those homes, rather than a condition report on the one you may buy.
For your search, the useful comparison is whether you would be happy with the included features at the quoted price. If you would change the flooring, counters or other finishes, consider that spending alongside another new build or a resale home you already like. Taylor can help compare those options without making the builder’s headline rate the whole conversation.
What can Taylor help you compare?
Taylor can help you compare a D.R. Horton home with other new builds and resale options at your budget: what is included, what you would want to change and how the price and incentives line up.
He can help gather the home’s written price, included features and offer details, then identify questions for the builder, lender and inspector. You do not have to assemble the whole package before making contact.
Before touring, confirm builder registration requirements and agree on representation services, compensation and any seller contribution. Builder payment of your representation costs is not assumed. Before signing, review deposits, cancellation terms, substitutions, inspection access and financing and completion deadlines; a Texas real-estate attorney can advise on legal interpretation.
D.R. Horton in Temple — practical buyer questions
What financing offer did D.R. Horton display when this guide was checked?
On October 18, 2026, the official Pecan Creek, Pepper Creek Crossing and Mesa Ridge pages displayed 5.50% fixed 30-year FHA and VA offers through DHI Mortgage, with FHA APR 6.212% and VA APR 5.657%. The advertised down payments are 3.5% for FHA and 0% for VA. The offer requires a contract on or after October 1, 2026 and closing by January 29, 2027, for an eligible principal-residence home. Credit approval, available funds and property restrictions apply; points may be required and additional closing costs apply. DHI is required for this rate, but not to purchase a home. Confirm written terms for your address.
Can I compare another lender with DHI Mortgage?
Yes. The displayed offer says DHI is required for its advertised rate, but not to purchase a home. Ask for written price and incentive terms under each lender, then compare Loan Estimates for the same home. Compare APR, points, financed fees, cash to close, monthly obligations and rate-lock conditions. The lower advertised rate does not by itself identify the better package.
Does the calculator show my full monthly payment?
No. It shows principal and interest for two fixed-rate scenarios on the same entered loan balance and term. It excludes taxes, insurance, mortgage insurance, HOA charges, maintenance, separate assessments and unfinanced fees. Include any financed fees in the balance you enter. It is not a loan quote or approval.
What does an advertised community starting price include?
It is a starting point from the builder’s community page, not a complete quote for a particular home. Ask for the address, plan, lot premium, options, included features, completion stage and incentive conditions. The four community examples in this guide were observed September 23, 2026; availability and prices can change.
How should I check schools and property taxes?
Confirm school assignment directly with the district for the home’s exact address. For taxes, identify every taxing entity, the relevant year, taxable values and any applicable exemptions. A mailing city, community name or purchase price alone does not establish either the school assignment or the tax bill.
Can I bring an independent inspector?
Ask for written inspection permissions, access requirements and notice deadlines under the actual contract before booking. Confirm which construction stages remain available to inspect and how findings will be addressed. Do not assume the builder must stop work or grant unrestricted access.
What warranty coverage should I expect?
Request the warranty booklet that applies to the specific home. Check coverage, exclusions, start and end dates, notice requirements and who handles each type of claim. A sample warranty or another buyer’s experience does not establish your contract’s terms. Keep written records and plan follow-up before applicable coverage ends.
How quickly can I move into a D.R. Horton home?
Ask about the actual home’s completion stage and written closing requirements, including financing, inspections, utilities and remaining work. This guide does not guarantee a 30–45-day closing or a construction completion date. Build an alternative housing plan around the uncertainties that remain.
What happens when I send the form to Taylor?
The form saves a request for manual follow-up about the community or home you are considering. A saved-request reference does not deliver a home match, loan quote, tax calculation or contract review. Discuss the scope of help and representation terms directly with Taylor.
What supports this guide?
Financing terms were checked on the official Pecan Creek, Pepper Creek Crossing and Mesa Ridge pages October 18, 2026. The four community starting prices and descriptions remain observations from September 23, 2026, not a refreshed inventory or MLS sales data. The earlier loan advertisement is preserved separately as historical evidence; only a property-specific written lender offer can resolve your terms.
- Pecan Creek, Pepper Creek Crossing, Mesa Ridge and Homestead: community descriptions and dated advertised prices.
- DHI affiliation disclosure and CFPB loan comparison guidance: lender relationship and comparing written offers.
- D.R. Horton documents and guides: obtain the warranty and contract documents applicable to your home.
Taylor’s field opinion is dated August 15, 2026; the Pecan Creek photographs were added to this guide on July 26, 2026. The embedded August video is historical and has the specific qualification beside it. This guide is independent of D.R. Horton and is not an offer of credit.
Let’s look at the whole deal before you decide.
Found a D.R. Horton home you like? I can help you compare its price, included features and written incentives with other homes you’d actually consider. We’ll look at what you’re getting, what you’d pay extra for, and whether another option deserves a look.
Still browsing? Tell me your budget and when you’d like to move.
Or leave your details below for manual follow-up.