Fort Hood BAH Rates 2026 + BAH-to-Home Calculator
Your 2026 Fort Hood rate
$1,695a month
E-5 · Sergeant (SGT) · with dependents
Without dependents: $1,530 a month
Select O-1E, O-2E or O-3E only when your servicing finance office confirms that category for your housing allowance. Do not select it solely because you previously served as an enlisted member or warrant officer.
Published 2026 table, TX286 (Fort Hood). Confirm yours at the official DTMO lookup.
Look up the published Fort Hood BAH table, then compare your confirmed allowance with one home’s loan payment, taxes, insurance and other ownership costs. The calculator shows a monthly shortfall or amount remaining; it does not determine a purchase budget or loan approval.
Content and calculator reviewed September 23, 2026 • Rate table: 2026 • Loan and property costs: your inputs, not current quotes
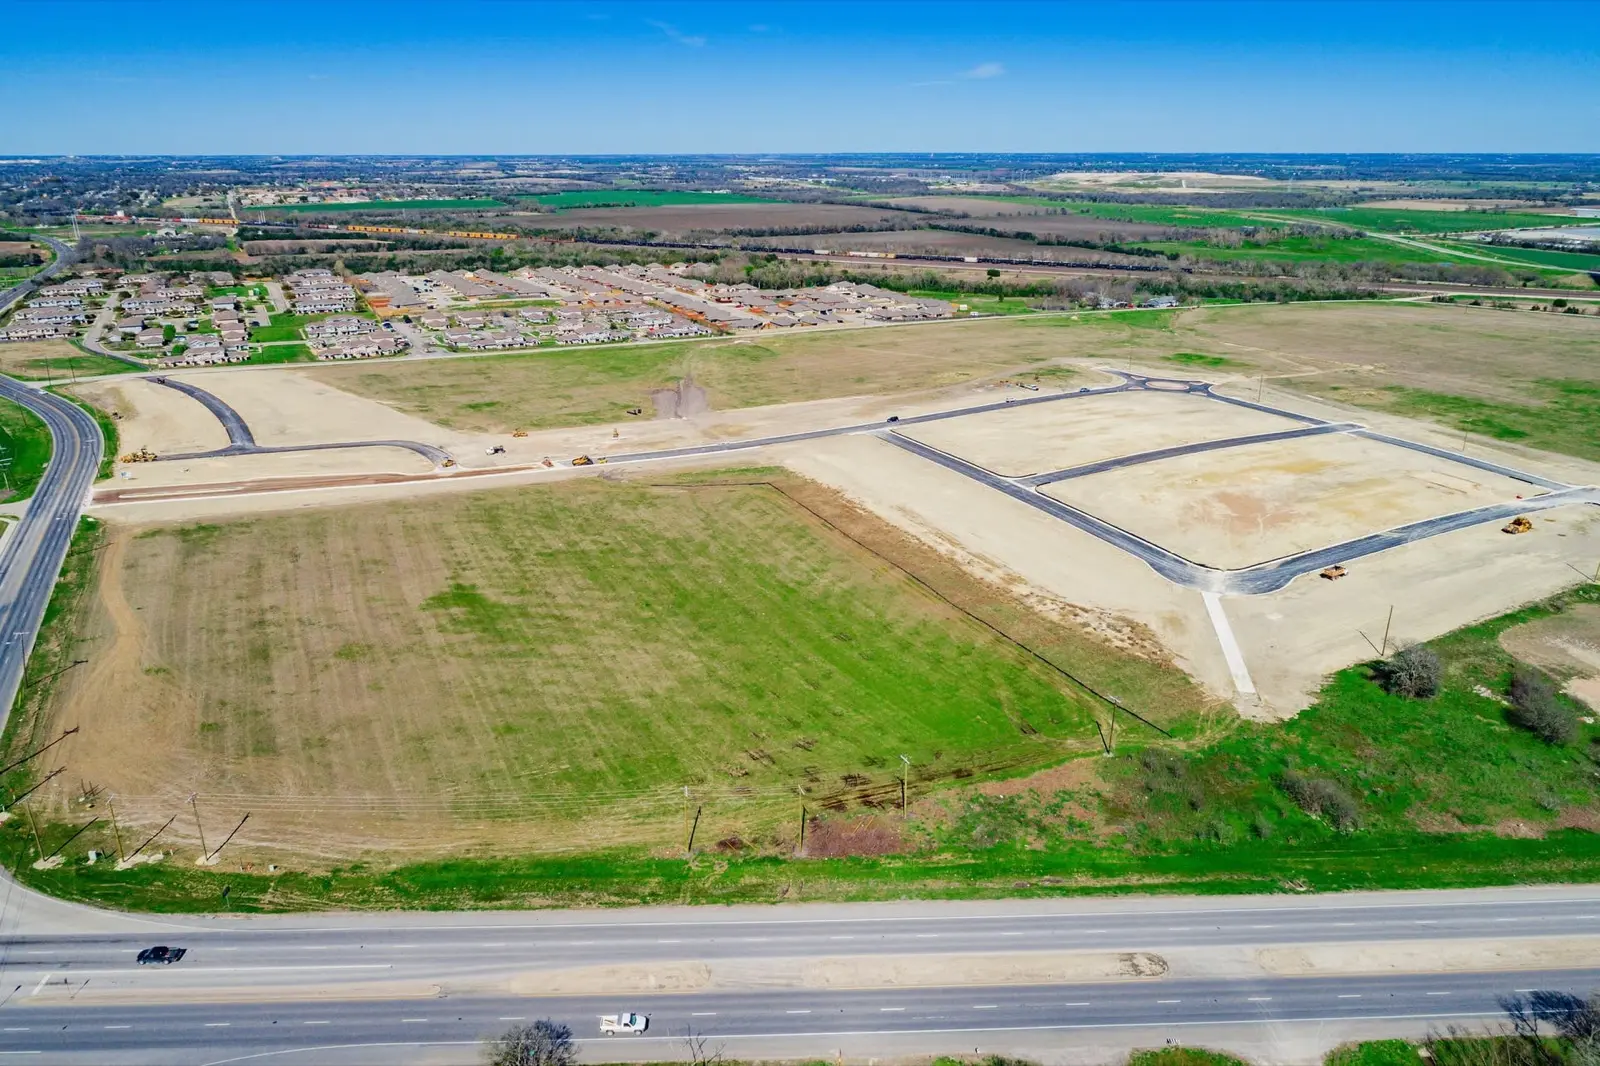
Aerial: South Pointe, TempleWhat is the 2026 Fort Hood BAH rate?
The published 2026 BAH table below lists $1,695 a month for E-5 with dependents and $1,530 without dependents for the official Fort Hood, TX military housing area (TX286). The full 2026 table of DTMO-published rates for all 24 categories runs from $1,662 a month with dependents and $1,374 without for E-1 to E-4, up to $2,787 with dependents and $2,361 without for O-7/O-7+. Check the official DTMO lookup and your applicable entitlement before using a figure. Your allowance alone does not establish what home you can afford.
Start with a particular home and written loan terms. Enter its financed loan balance, note interest rate and term; add property-specific costs. The result compares those modeled costs with the BAH amount you enter. It does not rank Temple, Belton, Killeen or Harker Heights by affordability.
Searching for Fort Cavazos BAH? Fort Cavazos is the former name of Fort Hood; see the naming question below.
Request a conversation about your Fort Hood housing search ↓
- Loan balance is not purchase price: include any financed funding fee in the balance you enter.
- Property tax is a separate input: use an estimate for the actual property and applicable exemptions, not a city-wide percentage of purchase price.
- A remaining amount is not disposable income: utilities, other household spending and upfront cash are outside this model.
How do this home’s monthly costs compare with your BAH?
Start from the worked example, a break-even row or a blank sheet. Every line says where its number came from, and a blank line stays unknown until you fill it.
Load a starting point
Replace your entries?
Your current entries stay as they are unless you choose Replace.
Complete all nine fields. Enter zero only for a confirmed zero amount; blank means unknown. Dollar fields accept cents and correctly grouped commas, such as 250,000.50, up to $100 million. Do not include a dollar sign. Interest: 0–30%, up to five decimal places. Term: 1–50 whole years.
What are the 2026 Fort Hood BAH rates? (24 published categories)
The published 2026 Fort Hood, TX (TX286) table below lists 24 published categories with and without dependents. Verify the year, duty location, dependency status and your applicable entitlement through the official DTMO BAH lookup. Where you choose to buy a home does not, by itself, establish which allowance you receive.
Tap a pay grade to make it your selection everywhere on this page.
Scroll horizontally to compare both monthly rates.
| Pay Grade | Rank | 2026 BAH w/ Dependents | 2026 BAH w/o Dependents |
|---|---|---|---|
| E-1 | Private (PV1) | $1,662/mo | $1,374/mo |
| E-2 | Private (PV2) | $1,662/mo | $1,374/mo |
| E-3 | Private First Class (PFC) | $1,662/mo | $1,374/mo |
| E-4 | Specialist / Corporal (SPC/CPL) | $1,662/mo | $1,374/mo |
| E-5 | Sergeant (SGT) | $1,695/mo | $1,530/mo |
| E-6 | Staff Sergeant (SSG) | $1,920/mo | $1,626/mo |
| E-7 | Sergeant First Class (SFC) | $2,070/mo | $1,668/mo |
| E-8 | Master Sergeant / 1SG (MSG/1SG) | $2,238/mo | $1,746/mo |
| E-9 | Sergeant Major / CSM (SGM/CSM) | $2,409/mo | $1,806/mo |
| W-1 | Warrant Officer 1 (WO1) | $1,938/mo | $1,665/mo |
| W-2 | Chief Warrant Officer 2 (CW2) | $2,139/mo | $1,743/mo |
| W-3 | Chief Warrant Officer 3 (CW3) | $2,346/mo | $1,812/mo |
| W-4 | Chief Warrant Officer 4 (CW4) | $2,433/mo | $1,950/mo |
| W-5 | Chief Warrant Officer 5 (CW5) | $2,544/mo | $2,109/mo |
| O-1E | Special officer category | $2,100/mo | $1,692/mo |
| O-2E | Special officer category | $2,313/mo | $1,788/mo |
| O-3E | Special officer category | $2,451/mo | $1,908/mo |
| O-1 | Second Lieutenant (2LT) | $1,731/mo | $1,623/mo |
| O-2 | First Lieutenant (1LT) | $1,917/mo | $1,689/mo |
| O-3 | Captain (CPT) | $2,340/mo | $1,833/mo |
| O-4 | Major (MAJ) | $2,577/mo | $2,076/mo |
| O-5 | Lieutenant Colonel (LTC) | $2,748/mo | $2,169/mo |
| O-6 | Colonel (COL) | $2,769/mo | $2,325/mo |
| O-7/O-7+ | Published grouped category | $2,787/mo | $2,361/mo |
Select O-1E, O-2E or O-3E only when your servicing finance office confirms that category for your housing allowance. Do not select it solely because you previously served as an enlisted member or warrant officer. Published rate year: 2026 · TX286 / Fort Hood. All 48 amounts checked against the official DTMO 2026 workbook on September 23, 2026. The final category follows the official lookup’s O-7/O-7+ label. Confirm your individual entitlement with your servicing finance office.
How is the applicable BAH area determined?
DTMO generally bases BAH on the permanent duty station ZIP code, pay grade and dependency status, not the home you choose to buy. This table is for TX286, labeled Fort Hood in the official 2026 download. Confirm your applicable allowance and any individual rate protection with your servicing finance office.
Use a confirmed allowance in the worksheet above, or continue to off-post housing options, where to live around Fort Hood, or the buy-vs-rent PCS calculator.
What does a monthly shortfall look like?
Hypothetical example, not a loan quote or local average: a $250,000 financed balance, 6% fixed note rate and 30-year term produce $1,498.88 in monthly principal and interest. Assume $4,800 annual property tax, $2,400 annual insurance, $50 monthly HOA, $0 monthly mortgage insurance and $200 maintenance reserve.
| Input or result | Monthly amount |
|---|---|
| Principal and interest | $1,498.88 |
| Tax set-aside | $400.00 |
| Insurance set-aside | $200.00 |
| HOA + mortgage insurance + maintenance | $250.00 |
| Modeled housing-cost subtotal | $2,348.88 |
| Assumed BAH for this example | $1,695.00 |
| BAH minus modeled costs | −$653.88 shortfall |
That shortfall must be considered alongside the rest of the household budget. Lower loan principal changes principal and interest, but a home’s tax estimate and insurance quote need their own review. An assumed zero mortgage-insurance amount is not a promise about your loan.
Illustration: what financed balance would break even with 2026 BAH in this example?
Illustration only: not a loan offer, a statement of what you can afford or a recommendation to spend your whole allowance on housing. Each row keeps the example’s other inputs (6% fixed note rate, 30-year term, $4,800 annual property tax, $2,400 annual insurance, $50 HOA, $0 mortgage insurance and a $200 maintenance reserve, or $850 a month outside principal and interest) and solves for the financed balance whose principal and interest uses the rest of the published 2026 Fort Hood (TX286) with-dependents amount, rounded down to the nearest $100.
| Pay grade, with dependents | 2026 BAH | Left for principal and interest | Break-even financed balance | Approx. price: first-use VA loan, $0 down, 2.15% fee financed |
|---|---|---|---|---|
| E-4 (same rate as E-1 to E-3) | $1,662 | $812 | $135,400 | $132,500 |
| E-5 | $1,695 | $845 | $140,900 | $137,900 |
| E-6 | $1,920 | $1,070 | $178,400 | $174,600 |
| E-7 | $2,070 | $1,220 | $203,400 | $199,100 |
| O-3 | $2,340 | $1,490 | $248,500 | $243,200 |
Enter a row’s balance with the example’s other amounts in the worksheet above to reproduce it; each shows between $0.12 and $0.51 remaining. At these terms, each additional $10,000 financed adds $59.96 a month in principal and interest. The price column divides the balance by 1.0215 because VA’s funding-fee chart (effective April 7, 2023; checked September 24, 2026) lists 2.15% of the loan amount for first use and 3.3% after first use when less than 5% is put down; borrowers who qualify for an exemption pay no fee, so their price and balance match. The VA down-payment conditions in the FAQ below still apply.
A higher rate, or higher tax, insurance or HOA amounts, lowers every balance, and a real home comes with its own tax estimate and insurance quote, so no row is a price target. A remaining amount is not disposable income: the costs listed as outside the subtotal above still apply, and lender qualification and your confirmed entitlement are separate checks.
For scale, the Temple buyer guide’s historical sample of 1457 closed-sale records (closings August 21, 2025–September 1, 2026) had a $269,900 median, with 232 records (15.9%) below $200,000 and 538 (36.9%) at $200,000–$274,999. Those are past Temple sale prices, not homes available now or homes a particular allowance will cover.
How should you compare Temple, Belton, Killeen and Harker Heights?
Choose a suitable home in each area you would consider, then run the same worksheet for each. Keep your allowance and household assumptions consistent; replace the loan and property inputs with that home’s documents.
| Decision | Bring to the comparison |
|---|---|
| Home price and financing | Written price, financed balance, note rate, term, cash needed and applicable lender fees for that home. Compare the Temple buyer guide with the Belton home guide to organize searches; neither establishes an available home or approval. |
| Taxes and insurance | Actual taxing entities and taxable values, applicable exemptions, current policy quotes, deductibles and flood coverage. The property-tax guide explains the property-specific method; its historical examples are not city-wide rates. |
| Work and school destinations | The exact work gate or building, shift and required arrival time; verify gate access and test the route. Confirm the home’s school assignment with the district for the enrollment year. A city name is not a school assignment or commute time. |
| PCS timing and flexibility | Report date, expected stay, occupancy requirements, moving cash and the cost of a later sale. Compare renting and buying for that timeline; there is no guaranteed break-even ownership period. |
Which documents should replace the assumptions?
- Ask the lender for written loan terms and an itemized estimate of upfront cash. The CFPB explains note interest versus APR: APR includes additional borrowing costs and should not be substituted into this payment formula.
- Ask for a property-specific annual tax estimate. A seller’s current bill may reflect exemptions or limits that do not apply to you; purchase price is not automatically the taxable value for every entity.
- Obtain insurance quotes for that home, association dues and any separate assessments. Include known repairs in upfront planning as well as a maintenance reserve.
- Confirm your applicable BAH with the official lookup and your servicing finance office. The table is a published schedule, not a determination of personal entitlement.
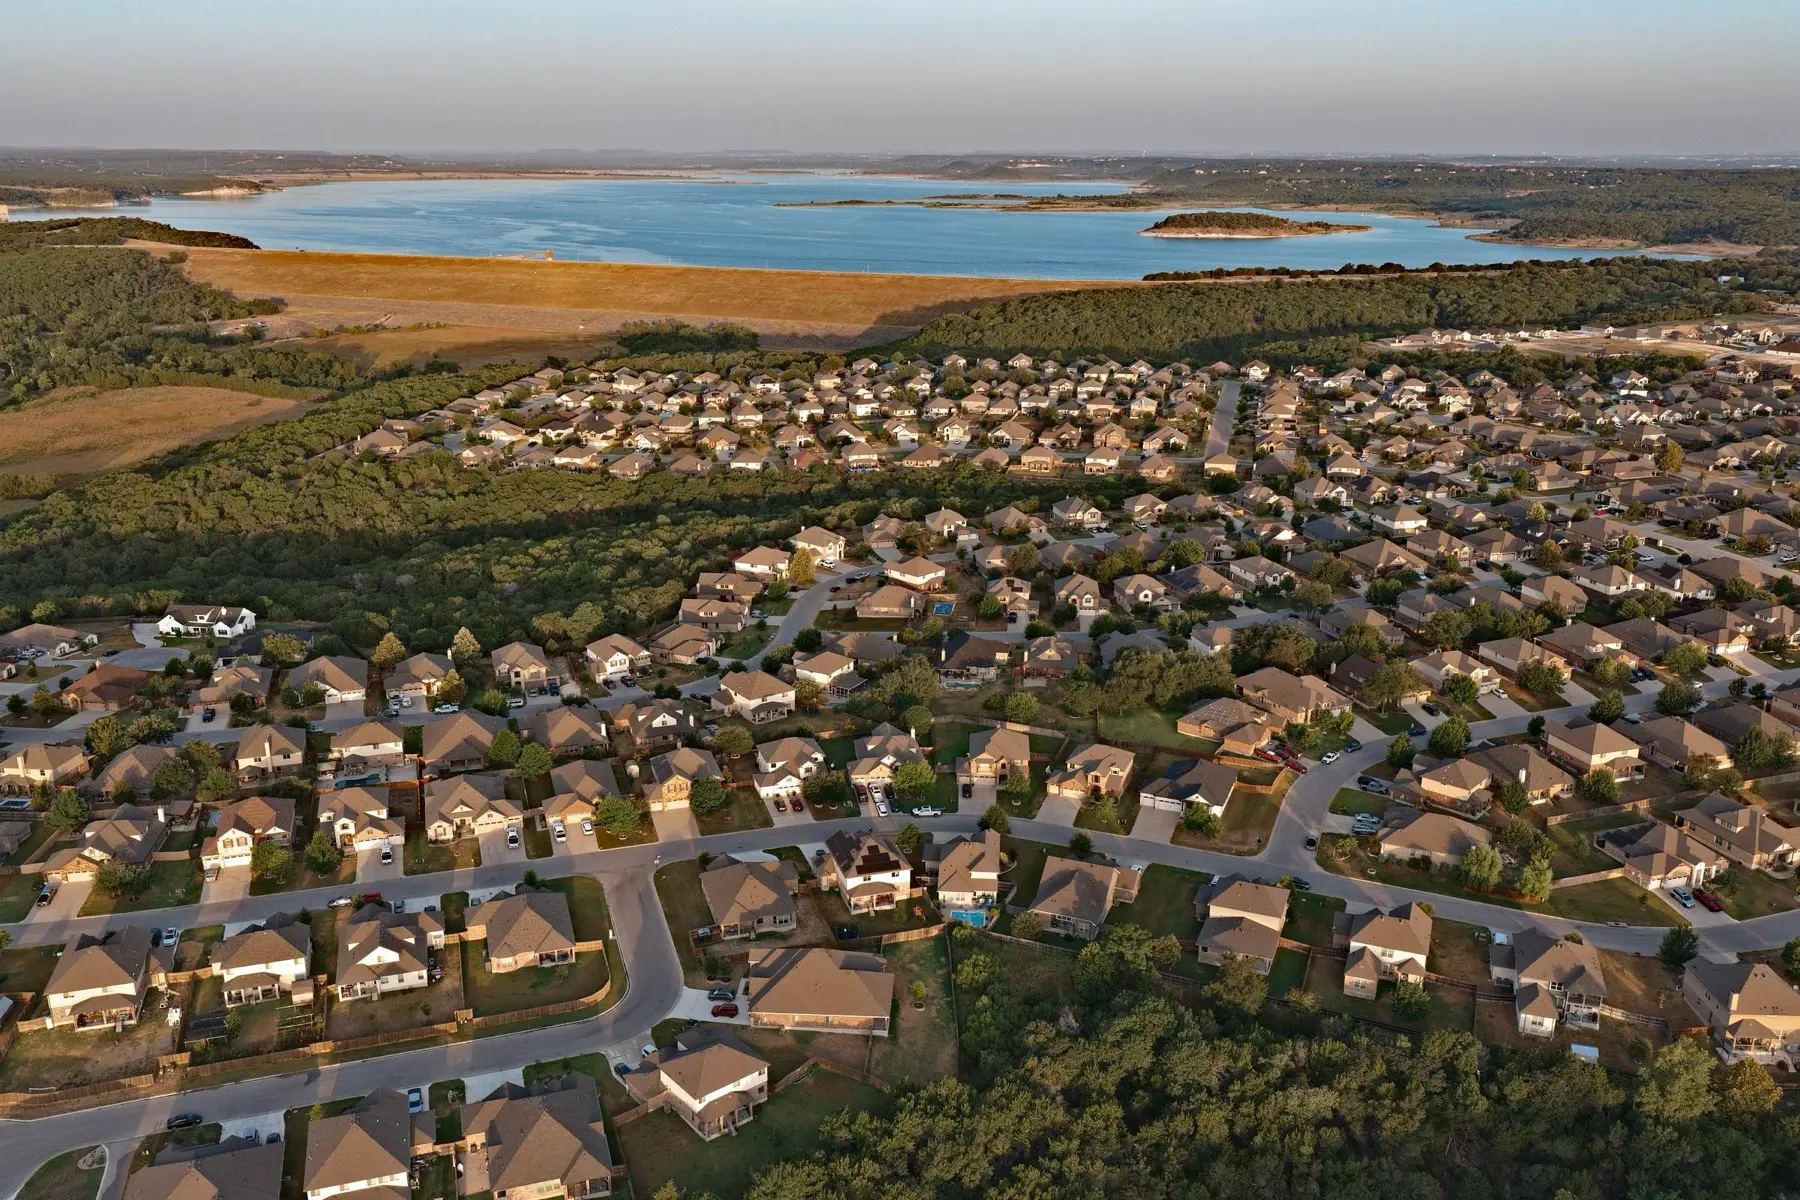
Killeen, Conder Park area: aerial from Taylor’s Fort Hood corridor shoot (shot KIL-P01).
Harker Heights or Nolanville: aerial from the same corridor shoot.
Ready to Find Your Fort Hood Home?
Discuss your report date, destinations, preferred homes and the costs you still need to confirm. Taylor can help organize the property search; your lender confirms loan qualification and terms.
Compare a particular home’s costs and your actual daily routes before choosing an area. A city name does not determine the tax bill or insurance premium. Background aerial: Morgan’s Point Resort.
Fort Hood BAH calculator questions
Are Fort Cavazos and Fort Hood the same installation?
Yes. Fort Cavazos is the former name of the same Central Texas installation now named Fort Hood. The Army held a ceremony on July 28, 2025, marking the return to the Fort Hood name in honor of Col. Robert Benjamin Hood. Confirm your applicable BAH through the official DTMO lookup and your servicing finance office.
What is the E-5 BAH rate shown for Fort Hood in 2026?
The published 2026 Fort Hood, TX (TX286) BAH table lists $1,695 a month with dependents and $1,530 without dependents for E-5. Verify your applicable year, location and entitlement through the official DTMO lookup and your servicing finance office before using an amount.
Does this calculator tell me how much house I can afford?
No. It compares a BAH amount you enter with modeled costs for a particular home. It calculates fixed-rate principal and interest from a loan balance, note rate and term, then adds the property costs you enter. Lender qualification, other household spending and upfront cash remain separate.
Should I enter purchase price or loan balance?
Enter the amount financed, including any financed funding fee. Purchase price, loan balance and taxable value can be different numbers. Enter property tax separately from an actual-property estimate; the calculator does not derive it from either price or loan balance.
What happens if BAH is less than the modeled housing costs?
The result shows a negative dollar amount labeled shortfall per month. A positive result is the amount remaining against the modeled subtotal, and zero is break-even at the displayed cent. Utilities and other household spending are outside the subtotal.
Can I leave unknown costs blank?
Leave an unknown cost blank while you gather information; the calculator will hide your completed result until every field is valid. Enter zero only when the amount is confirmed to be zero. No tax, insurance or maintenance amount fills a missing personal field automatically. The worked-example and break-even controls deliberately load labeled hypothetical entries; the example view leaves your entries unchanged. Clear a loaded illustration before entering your own confirmed figures.
Can a VA loan mean no down payment and no mortgage insurance?
A VA-backed purchase loan may require no down payment when the sales price does not exceed the appraised value and the available entitlement and lender requirements support the loan. Insufficient remaining entitlement or a price above the appraisal can mean cash is needed. VA-backed purchase loans have no monthly mortgage insurance, but still require eligibility and lender approval. Confirm any funding fee, exemption and other closing costs with the lender; include any financed funding fee in the loan balance once.
Does choosing Belton instead of Temple guarantee lower housing costs?
No. Compare the actual home price, loan terms, taxing entities, taxable values, exemptions, insurance, association costs, condition and your daily routes. The calculator does not award a city-wide affordability winner.
What happens when I submit the Fort Hood housing form?
The form requests manual follow-up from Taylor about your move and housing questions. Submitting it does not automatically create a personalized plan, confirm a home or establish a response deadline. Discuss your report date, destinations, housing needs and lender-confirmed budget before compiling a shortlist.
Before you take the math to an agent
I’m a first-time buyer using a VA loan, and he made the process feel clear and manageable from start to finish. … If you want an agent who’s professional, responsive, and truly has your back, Taylor is the one!
Arleene SilvaFirst-time buyer · VA loanRead the review on Google →Excerpt · full review at the link
On the record
- 57Google reviews · 5.0 averageverified Read them →
- 4Zillow reviews · 5.0 averageverified Read them →
Public reviews, quoted exactly and linked to the source. Counts are per platform and never added together. Read the full ledger →
Want help translating the BAH math into neighborhoods?
Use the form to request manual follow-up about your report date, destinations and housing priorities. The “Request PCS follow-up” button records a request; it does not generate or deliver a plan automatically or promise a response time.
Keep going on your Fort Hood move
- Military Relocation to Temple TXPlan the move, compare housing areas and identify questions for your lender.
- Fort Hood Off-Post HousingOrganize off-post housing options, then verify the actual home and route.
- Military Buy vs Rent PCS CalculatorExplore renting versus buying for your PCS timeline and verify the assumptions.
- Where to Live Near Fort HoodCompare corridor towns and verify property costs, routes and school assignments.
- Temple-Area NeighborhoodsBrowse neighborhood guides and build an actual-home shortlist.
- Home ValuationAlready own near Fort Hood? Request a home value estimate before your next move.
Sources and review
Taylor Dasch · EG Realty. Content, calculator and primary-source review: September 23, 2026. BAH amounts are the published 2026 TX286 schedule; individual entitlement and rate protection require confirmation. Loan and property inputs are your assumptions or quotes, not a current advertised mortgage offer.
- DTMO BAH lookup and official annual downloads establish the published schedule and duty-station lookup. DTMO rate-protection guidance explains why an individual payment may differ from a newly published rate.
- VA purchase-loan guidance, eligibility requirements, available entitlement and loan limits and funding fees and closing costs explain conditional benefits, qualification and cash obligations. A Certificate of Eligibility is not loan approval.
- CFPB interest-rate and APR guidance distinguishes the payment rate from the broader cost of borrowing. Texas Comptroller property-value guidance and the linked local tax guide support property-specific budgeting.
For the next step, gather the home address, written loan terms, tax estimate, insurance quotes and association charges. Request a conversation through the form about the home search; confirm lending and pay-entitlement questions with the appropriate lender or finance office.